
Executive summary (Direct answer): How to pay for backyard renovation can vary significantly based on your goals and financial situation. Understanding your options can help you make informed decisions about funding your project effectively. depends on project size and timing: use savings or phased cash for small updates; consider unsecured personal loans or in-house contractor financing for mid-sized projects; and rely on HELOC (Home Equity Line of Credit), Home Equity Loan, or cash-out refinancing for major hardscape or pool work. Compare APRs, monthly payments, and collateral risk, keep a 10–15% contingency, and get three local contractor and lender quotes before committing.
Dreaming of a new backyard but unsure how to fund it? Connect your lifestyle priorities to a phased plan and realistic budget so your outdoor space becomes a durable investment in your home and everyday living.
Read the financing breakdown below or jump straight to the financing section for method-by-method comparisons: Go to Financing Options.
Key Takeaways
- Priority today: Outdoor living spaces boost appeal and resale value.
- Start with a budget: Know your maximum spend before choosing materials or hires.
- Match financing to the project: HELOC/Home Equity Loan for large projects, personal loans or savings for mid-sized ones.
- Small changes count: Modest landscaping and hardscape improvements can raise home value and daily quality of life.
- Plan and phase: Phasing makes projects affordable and lets you use parts of the yard while later phases complete.
Why are backyard renovations a priority for homeowners today?

Direct answer: Backyard renovations are rising in priority because well-planned outdoor living spaces increase usable living area, enhance lifestyle, and often improve home value — prioritizing durable, high-ROI features and phased budgets delivers the best financial outcomes.
Context: Many homeowners want a dream backyard but worry about costs. National surveys show growing interest in outdoor projects; local demand and costs vary, so use national figures as a guide and secure local quotes to refine your plan.
Balancing higher-end landscape design with everyday use requires smart prioritization: choose features that both improve daily living and align with neighborhood expectations to protect home value and resale prospects.
| Project Type | Average Cost | Potential ROI |
| P atio Installation | $3,000 – $10,000 | 70% – 80% |
| Deck Construction | $4,000 – $15,000 | 65% – 75% |
| Landscaping | $1,500 – $5,000 | 50% – 60% |
Typical national averages — local rates may be higher or lower. For a $10,000 budget example, allocate roughly $4,000 for hardscape (small patio), $3,000 for plantings and soil improvements, and $3,000 for lighting, furniture, and contingency. That mix improves daily living and curb appeal without overinvesting in finishes that won’t pay off in your market.
For specific contractor guidance on patios and landscape work, see this guide and the Magnolia resource on backyard living spaces: Backyard Renovation & Living Spaces. Get at least three local estimates and ask contractors about typical ROI in your neighborhood to align design to property value expectations.
Key Takeaway: Prioritize durable, high-ROI elements and phase work to match your budget and local market norms.
What are the key terms and baseline costs to understand before renovating your backyard?
Direct answer: Know the difference between landscaping (plants and soft features), hardscaping (patios, walkways, structural elements), and home improvement (any work that increases function or value); expect basic landscaping to cost roughly $4.50–$12 per sq ft, while hardscaping and design run higher—always get local bids and plan contingencies.
Definitions (at a glance): Landscaping = plants, soil, irrigation, and aesthetic elements; Hardscaping = patios, walkways, retaining walls, and structural outdoor features; Home improvement = projects that increase a property’s function or value (consider maintenance and lifecycle costs when choosing materials).
Understanding baseline costs helps homeowners create a realistic plan and avoid surprise expenses. Regional factors—climate, soil, permit requirements, and local labor rates—shift these averages, so treat the figures below as national guidance and confirm with three local contractor quotes.
Typical price ranges (national averages): landscaping work commonly runs $4.50 to $12 per sq ft for basic plantings and lawn tasks; landscape design and hardscaping typically cost more due to materials and labor intensity. For small updates, use cash or savings to avoid interest; for larger scopes, evaluate how interest rates and loan terms affect the total amount you’ll repay.
| Landscaping Type | Cost per Square Foot | Hourly Rate |
| Basic Lawn Care | $4.50 – $12 | $50 – $100 |
| Landscape Design | $10 – $20 | $75 – $150 |
| Hardscaping | $15 – $30 | $100 – $200 |
Regional factors such as climate, soil conditions, and local labor rates will change these numbers. Plan for a 10–15% contingency, ask contractors for itemized estimates, and compare scopes of work. To see a sample regional breakdown, review this Magnolia resource: this resource.
Key Takeaway: Use these baseline costs as starting points, get three local estimates, and budget a contingency so your plan protects home value and aligns with your goals.
What are the best financing options and how to pay for backyard renovation projects?

Direct answer: Match the financing to project size — use cash or phased budgets for small updates; unsecured personal loans or in-house contractor financing for mid-sized projects; and HELOC (Home Equity Line of Credit), Home Equity Loan, or cash-out refinancing for major hardscape or pool work. Compare APRs, monthly payments, and collateral risk, and get multiple lender quotes before committing.
Understanding financing options helps protect your home value while keeping monthly payments manageable. Secured options that integrate home equity typically offer lower interest rates and larger sums; unsecured personal loans provide speed and no-collateral convenience but usually at higher interest.
National average APRs (estimates — verify with lenders as of July 2026): Home Equity Loan ~8.9% APR; HELOC ~9.1% APR; Personal Loans 10%–15% APR (credit-dependent). HELOCs often have variable rates and a draw period with interest-only payments; home equity loans are fixed-rate lump sums.
| Financing Option | Average Interest Rate | Pros |
| Home Equity Loan | ~8.9% | Lower rates, fixed payments, good for one-time large amounts |
| HELOC | ~9.1% | Flexible access, pay interest only on amounts used (good for phased projects) |
| Personal Loan | 10% – 15% | Unsecured, fast approval, no collateral required (higher rates) |
| Cash-Out Refinancing | Varies | Replace mortgage to access large sums, may lower rate if market favors you |
Backyard Renovation Funding Methods (extractable comparison)
| Financing Method | Average Interest Rate / APR Range | Typical Approval Speed | Best For (Budget Tier / Project Size) | Key Pros & Cons |
| HELOC (Home Equity Line of Credit) | ~7% – 12% APR (variable) | 1–4 weeks | High-end projects ($35,000+); phased landscaping | Pros: Flexible draws, interest-only options during draw period. Cons: Variable rate, uses home as collateral. |
| Home Equity Loan | ~6% – 11% APR (fixed) | 2–6 weeks | Large one-time costs (pools, full hardscape) | Pros: Fixed payments, predictable. Cons: Secured by home, closing costs. |
| Cash-Out Refinance | Varies (depends on mortgage rates) | 3–8 weeks | Very large projects or consolidated debt | Pros: Access large sums, potential lower rate. Cons: Resets mortgage terms, closing costs. |
| Unsecured Personal Loan | ~7% – 20% APR | Days to 2 weeks | Mid-tier projects ($10k–$35k) | Pros: No collateral, fast approval. Cons: Higher rates, lower max amounts. |
| In-House Contractor Financing | Varies (often promotional) | Days to weeks | Mid-tier to large projects (depends on offer) | Pros: Convenient, sometimes 0% promotions. Cons: Watch fees and balloon payments. |
| Cash / Savings | 0% cost of borrowing | Immediate | Small projects ($1k–$10k) | Pros: No interest. Cons: Depletes emergency funds. |
Decision steps (quick):
- Estimate total amount: include a 10–15% contingency for site surprises.
- Match financing to scope: use HELOC/Home Equity Loan for large or phased projects; personal loans or in-house financing for mid-tier; cash or zero-interest cards for small jobs.
- Compare true cost: compare APR, origination fees, prepayment penalties, and monthly payment impact.
- Check credit: better credit secures lower rates — target 700+ for competitive APRs.
Monthly payment example: A $30,000 loan over 10 years at 8.9% APR has estimated payments near $378/month — run your own amortization with fees included before you commit.
Before you apply — checklist: compare APRs and fees from at least three lenders, request prequalification offers, confirm fixed vs. variable terms, get written loan estimates, and run payment scenarios with a financing calculator. For local contractor searches, consider using a mapped resource: Find local contractors, and consult Magnolia for scope and living-space planning: Backyard Renovation & Living Spaces.
Key Takeaway: Choose financing that aligns with project size and timeline — equity integration (HELOC/home equity loan) for large builds, unsecured loans or in-house financing for mid-range, and cash/phasing for small projects — and always verify current interest rates and lender terms.
How much do backyard renovation projects cost and what ROI can I expect?

Direct answer: Typical cost tiers: small projects ($1k–$10k), mid-range ($10k–$35k), and major renovations ($35k+) — patios and landscaping usually deliver the best cost-to-value ratio, decks add reliable resale value, and pools offer strong lifestyle value but slower resale recovery. Match financing to the tier to protect home value and monthly payments.
Quick overview: Investing in your backyard improves daily living and can increase home value when you prioritize durable, high-ROI features and avoid overcapitalization. Below are typical national cost examples and sample budgets to help you self-segment and choose the right financing and design approach.
ROI at a glance:
- Patios & modest landscaping — best cost-to-value: relatively low cost, high resale recovery.
- Decks — solid resale value: good balance of daily usability and ROI.
- Pools — lifestyle-first investment: high cost, variable resale recovery depending on market.
Typical national cost examples (confirm local pricing):
- Pool: $39,000–$70,000 depending on type and sitework — great lifestyle payoff; resale recovery varies by region.
- Patio: $3,000–$10,000 — often recovers a high percentage of cost at resale.
- Deck: $4,000–$15,000 — solid resale value and daily usability.
- Lawn care / plantings: low upfront cost with notable curb-appeal benefits.
Sample budgets and suggested financing matches:
- Small refresh — ~$5,000: targeted plantings, new mulch, lighting, basic furniture. Best financed with cash savings or a short-term zero-interest promotion.
- Mid-range project — ~$25,000: patio or small deck, upgraded plantings, lighting, modest hardscape. Consider an unsecured personal loan or in-house contractor financing for a phased landscaping budget.
- Major renovation — $60,000+: pool or full landscape redesign with hardscaping and outdoor kitchen. Equity integration (HELOC, Home Equity Loan, or cash-out refinance) is typically best for large sums.
Budgeting tips: always include a 10–15% contingency for unforeseen site costs; factor recurring maintenance (sealants, irrigation, pool upkeep) into annual home-improvement expenses; prioritize durable materials that reduce long-term costs.
Example allocation: A $10,000 budget might break down to $4,000 patio, $3,000 landscaping, $1,000 lighting, and $2,000 furniture/contingency — a balanced mix that improves daily use and protects property value without overinvesting in luxury finishes.
For additional cost breakdowns and planning tools, see this practical guide: How much does it cost to renovate your landscape, and Magnolia’s resource on planning living spaces: Backyard Renovation & Living Spaces. Use an interactive budget calculator to test payment scenarios and align renovation costs with your chosen financing options.
Key Takeaway: Choose features that match your lifestyle and neighborhood norms, budget a contingency, and align financing (cash, personal loan, or equity) to your project tier to maximize ROI and minimize financial strain.
How do I plan and fund a backyard renovation step-by-step?

Direct answer: Break the project into phases, set timelines, and match financing to each stage—cash or short-term credit for small refreshes, personal loans or in-house contractor financing for mid-tier work, and HELOC/Home Equity Loan or cash-out refinancing for major builds—so you improve your space without overextending payments.
Turn ideas into a workable plan: define scope, secure permits, get three comparable bids, and allocate funding by phase so parts of your yard are usable while later phases complete.
If you have $X, start here:
- $5,000 (Small refresh): DIY plantings, fresh mulch, lighting — finance with cash or a short-term zero-interest card.
- $25,000 (Mid-range): Install a patio or small deck first, then landscape beds and lighting — consider an unsecured personal loan or in-house contractor financing for a phased landscaping budget.
- $60,000+ (Major): Build hardscape foundations and utilities first (permit stage), then add pool or outdoor kitchen in later phases — equity integration (HELOC or Home Equity Loan) is often the best option for large amounts.
Essential steps:
- Permits & rules: Secure permits and confirm HOA and municipal codes before you spend to avoid costly rework.
- Design & scope: Create a detailed design and itemized scope so contractor bids are comparable.
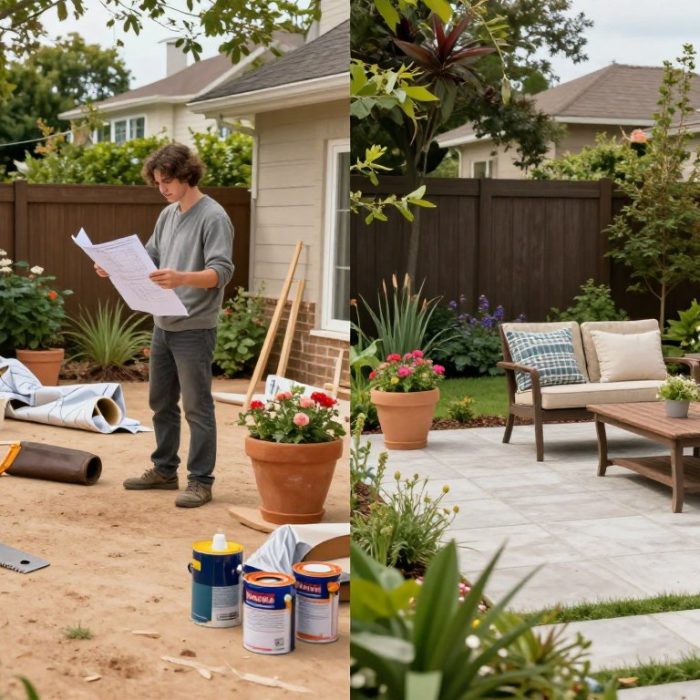
- Phasing: Start with hardscape (foundation, drainage), then add planting and features so the yard is usable early.
- Track payments: Link each payment to a deliverable in a spreadsheet or project tool and request phased payment schedules from contractors.
- Contingency: Keep a 10–15% contingency for unforeseen site work and timing delays.
| PhaseKey ActivitiesEstimated | Timeframe | |
| Planning | Design layout, secure permits, get 3 bids | 1-2 months |
| Hardscape | Install patios, decks, grading, utilities | 2-3 months |
| Landscaping | Plant trees, install irrigation, finalize features | 1-2 months |
Financing map by budget tier (compact):
- Low budget ($1k–$10k): Cash savings, phased landscaping budget, or 0% promotional credit.
- Mid budget ($10k–$35k): Unsecured personal loan or in-house contractor financing — fast approval and manageable monthly payments.
- High budget ($35k+): HELOC (Home Equity Line of Credit), Home Equity Loan, or cash-out refinancing for larger amounts and lower interest rates (see Financing section).
Practical tips: ask contractors for a written phased payment schedule (deposit, mid-project, completion), request itemized change-order pricing, and reserve a small payment buffer to keep the project on track. Download a printable phase checklist and use a schedule estimator to visualize time and payments for your specific project — see Magnolia’s planning resources for templates and contractor comparison tools: Backyard Renovation & Living Spaces.
Key Takeaway: Plan by phase, match financing to each stage, and enforce written scopes and phased payments to protect your budget and timeline.
What common financing and design mistakes should you avoid when renovating your backyard?

Direct answer: Avoid overcapitalization and risky financing—spend within neighborhood norms, verify permit/HOA requirements, and choose loan terms you can comfortably repay. These precautions protect home value and prevent long-term payment stress.
Avoiding common mistakes saves money and preserves your home’s resale potential. Appraisers and agents emphasize comparable sales and overall condition; expensive one-off features rarely pay off if they exceed neighborhood expectations.
Red flags (and what to do):
- Big spend, low return: If a feature exceeds neighborhood norms — ask an appraiser whether it will add resale value before you sign.
- HOA / permit risk: Confirm HOA rules and municipal permits early — get approvals in writing to avoid fines or rework.
- Risky financing: Beware balloon payments, steep deferred-interest offers, or unaffordable schedules — compare total cost and monthly payment across options.
- One-off trends: Avoid fleeting styles; choose timeless design and durable materials to reduce lifecycle costs.
Practical checks before you sign:
- Material alternatives: Ask contractors for mid-range, durable options and lifecycle cost comparisons.
- Comparable-sales data: Get neighborhood comps from an agent or appraiser to gauge realistic ROI.
- Payment schedule: Require a written payment plan tying disbursements to completed milestones.
Quick financing safety checklist:
- Credit: Check your score and correct errors — higher credit lowers loan rates.
- Terms: Compare APR, origination fees, fixed vs. variable rates, and prepayment penalties.
- Contingency: Maintain a 10–15% contingency and an emergency fund to avoid risky defaults.
Safer financing practice: if you have equity, compare secured options (home equity loan/HELOC) against unsecured personal loans — secured loans often lower rates but use your home as collateral. Cross-check financing choices with the Financing section and consult local lenders or Magnolia for tailored advice.
Key Takeaway: Match spending to neighborhood norms, verify permits, and choose transparent, affordable loan terms to protect value and avoid costly mistakes.
What are the final steps to fund and start my backyard renovation?
Direct answer: Confirm your total budget, choose financing that matches the project tier, get three contractor and lender quotes, and start with the highest-ROI phase first so payments and work remain manageable.
Successfully funding your outdoor project requires matching financing to the size and timing of your renovation, prioritizing high-ROI improvements, and planning phases so payments and work stay affordable. Whether you use a Home Equity Loan, HELOC (Home Equity Line of Credit), unsecured personal loans, or savings, pick the option that preserves home value and fits your monthly budget.
Careful planning and phased execution reduce financial stress and help you meet both design and investment goals. Avoid overspending on luxury finishes that exceed neighborhood norms; instead focus on practical improvements that enhance daily living and resale value (patios, decks, smart landscaping).
Next steps (actionable): download the 3-step financing checklist, run numbers in a loan calculator, and get three local contractor and lender quotes to compare APRs, fees, and monthly payments. For local pros, use this mapped resource: Find local contractors. If you want expert help, contact a vetted landscape professional or a mortgage advisor to discuss personalized terms — consider reaching out to Magnolia for a project quote: Backyard Renovation & Living Spaces.
Disclaimer: This article provides general information and is not professional financial or legal advice. Interest rates and lender terms change frequently — consult licensed lenders or a financial advisor for current rates and personalized loan terms. Last updated: July 2026.